The November 2025 ISA Budget Reforms: What Changed and What It Means
Update, 29 October 2026: the Autumn Budget 2026 reversed the cash ISA cut described here, so the cash ISA limit stays at £20,000 for all savers over 18. It also raised the planned savings tax rates to 24%, 44% and 49% from April 2027, and set April 2029 for the First Time Buyer ISA. On 29 October 2026 HMRC confirmed that the transfer ban, the 22% charge and the money market fund rule below won’t take effect either, and that the regulations that set them are due to be revoked. The latest position is in my Autumn Budget 2026 article, linked further down.
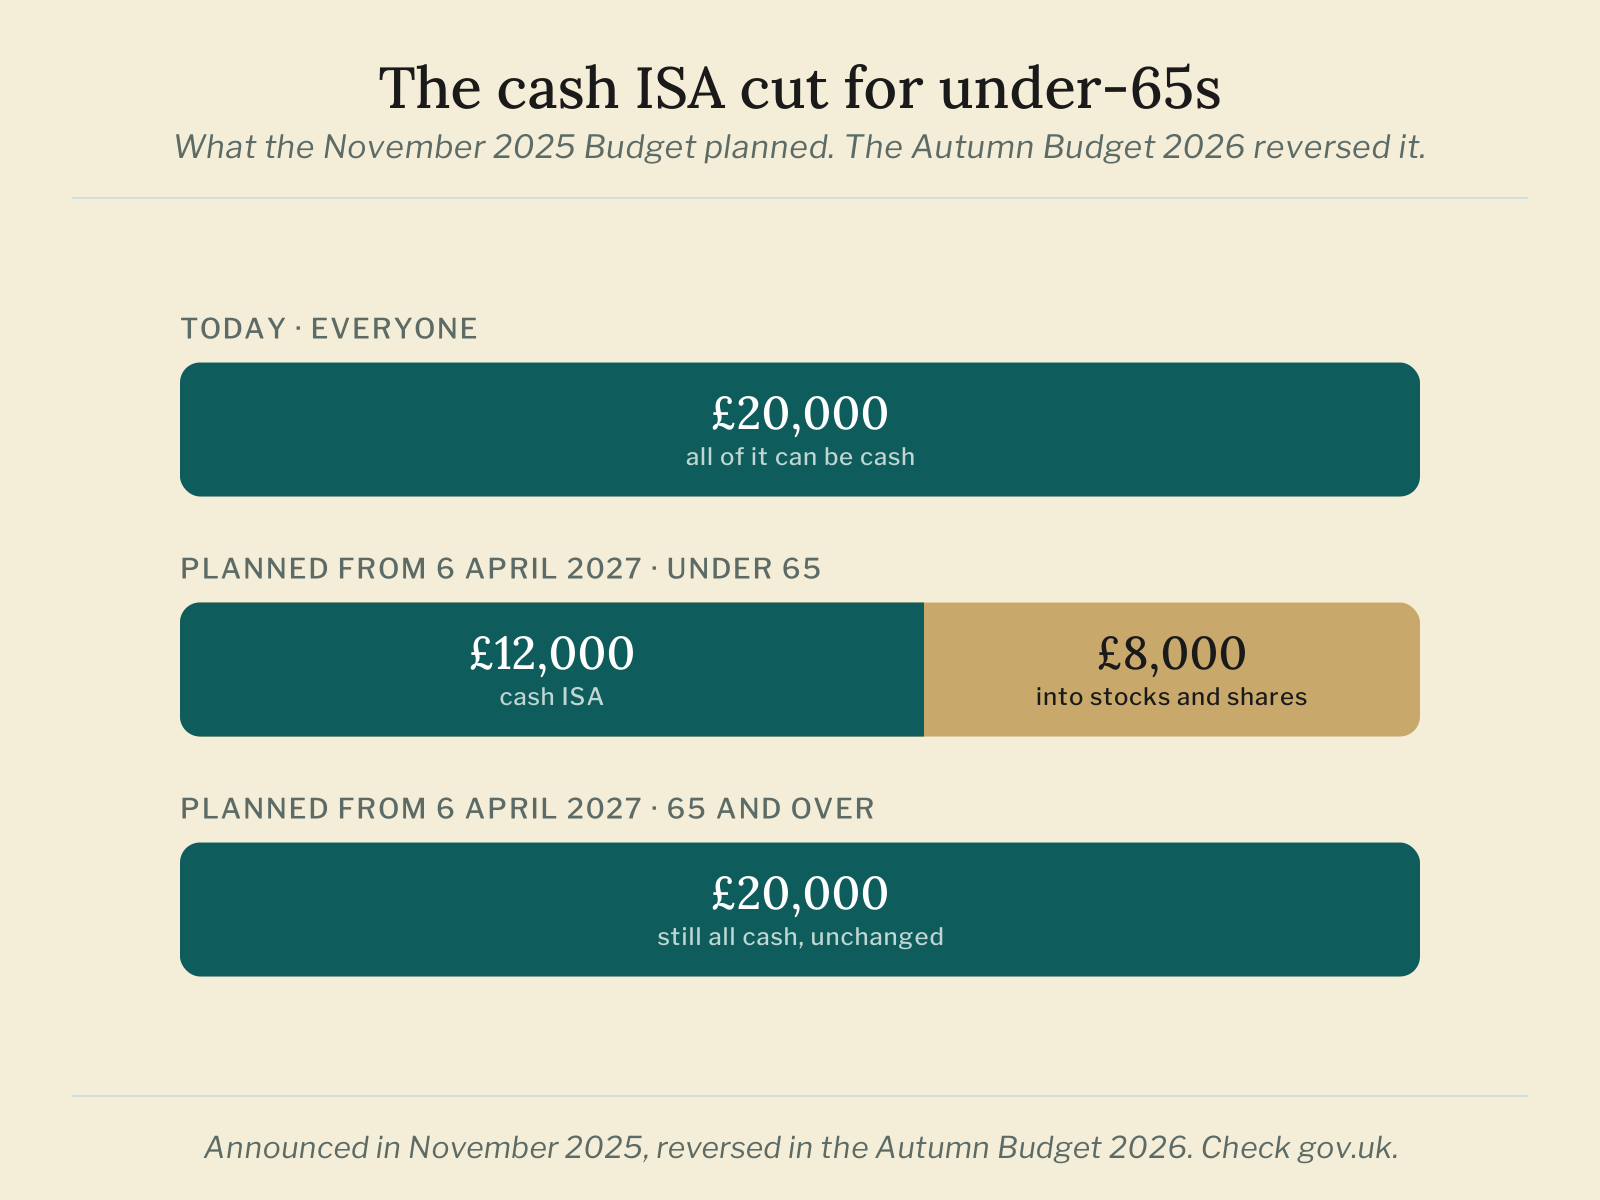
The November 2025 Budget cut how much under-65s can put into a cash ISA each year, from £20,000 to £12,000, starting on 6 April 2027. The overall £20,000 allowance does not change, so the other £8,000 can still go into a stocks and shares ISA, and over-65s keep the full £20,000 in cash. From the same date, it planned to stop under-65s moving money from a stocks and shares ISA into a cash ISA, and to charge 22% on interest from uninvested cash inside a stocks and shares ISA. All three have since been dropped.
The detail, and the timing, matter more than the panic. Here is what the Chancellor announced in the Autumn Budget on 26 November 2025, when each change bites, and what it means in practice.
The ISA changes at a glance
| Change | From | Who it affects |
|---|---|---|
| Cash ISA limit falls from £20,000 to £12,000 (reversed in Budget 2026) | 6 April 2027 | Under-65s |
| No transfers from stocks and shares ISAs into cash ISAs (now dropped) | 6 April 2027 | Under-65s |
| Flat 22% charge on interest from uninvested cash in a stocks and shares ISA (now dropped) | 6 April 2027 | Anyone holding cash in one |
| Dividend tax up 2 points, to 10.75% (basic) and 35.75% (higher) | 6 April 2026 | Dividends earned outside an ISA |
| Tax on savings interest up 2 points, to 22%, 42% and 47% (raised to 24%, 44% and 49% in Budget 2026) | 6 April 2027 | Interest earned outside an ISA |
| Lifetime ISA closes to new savers when the First Time Buyer ISA launches | April 2029 (set in Budget 2026) | New savers; existing holders keep current rules |
| Overall £20,000 ISA allowance | Unchanged | Everyone |
The headline change
From 6 April 2027, the amount under-65s could pay into a cash ISA each year was due to fall from £20,000 to £12,000, a cut the Autumn Budget 2026 later reversed. The rest of your allowance, the other £8,000, is still yours to use, but it has to go into a non-cash ISA, such as a stocks and shares ISA. The stated aim is to nudge more people from saving towards investing.
What is not changing
- The overall ISA allowance stays at £20,000 a year.
- The stocks and shares ISA and innovative finance ISA limits stay at £20,000.
- If you are 65 or over, you keep the full £20,000 cash ISA allowance.
- Nothing changes right now. The current rules run for the rest of the 2026/27 tax year, so you can still put the full £20,000 into cash until 6 April 2027.
A transfer restriction, now dropped
Alongside the cash cut, from April 2027 under-65s were not to be allowed to transfer money out of a stocks and shares ISA or an innovative finance ISA into a cash ISA. It was an anti-avoidance measure designed to stop people sidestepping the new cash limit. HMRC has since confirmed it won’t take effect, so transfers in both directions carry on as before.
Tax rises that make the ISA matter more
Two other Budget changes raise the value of sheltering money inside an ISA at all. The tax on dividends rose in April 2026, with the basic rate going from 8.75% to 10.75% and the higher rate from 33.75% to 35.75%. And the tax on savings interest rises by 2 percentage points from April 2027. Inside an ISA, none of those taxes apply, so as tax outside the wrapper goes up, the wrapper is worth more.
The Lifetime ISA
The Budget also announced that the Lifetime ISA would be replaced by a new First Time Buyer ISA. Budget 2026 has since set its launch for April 2029, and the government published its response to the consultation on 28 October 2026, confirming up to £4,000 a year and a 25% bonus worked out on the final balance, capped at £20,000. The Lifetime ISA is planned to close to new savers when the First Time Buyer ISA launches in April 2029, at the time of writing. Existing Lifetime ISA holders can keep contributing under the current rules, so nobody with one is losing out. I explain what the consultation proposed, and what was confirmed, in the First Time Buyer ISA consultation.
A 22% charge on cash inside investment ISAs, now dropped
From 6 April 2027, interest earned on cash held inside a non-cash ISA, such as a stocks and shares ISA or an innovative finance ISA, was to be charged at a flat 22%. HMRC confirmed this in a policy paper in June 2026. It was another anti-avoidance measure, aimed at stopping people using an investment ISA to shelter cash once the cash ISA limit was cut. It was a flat rate, so it would have applied whatever your income tax band, and only to interest from uninvested cash, never to your shares, funds or dividends. The 22% was set to match the basic rate on savings interest planned at the time. The regulations were made on 10 September 2026, after a technical consultation that closed on 2 August, and were due to come into force on 6 April 2027. On 29 October 2026 HMRC confirmed they’re due to be revoked, along with the rule on money market funds, as I set out in what the Autumn Budget 2026 means for your ISA.
What it means in practice
With the cash ISA cut reversed, nothing changes for cash ISA savers: the £20,000 limit applies to cash and investments alike, at the time of writing. The bigger picture is still a government steer towards investing, but the April 2027 rules that would have pushed it are gone. Whether that suits you depends on your own circumstances and timescales, and this is information, not advice. As ever, the official rules live at gov.uk, and the detail here can change.
What actually changed
The Budget planned to cut the cash ISA limit for under-65s from £20,000 to £12,000 from April 2027. The Autumn Budget 2026 reversed it, so the limit stays at £20,000. The overall £20,000 allowance and the stocks and shares ISA limit are unchanged.
When does it take effect?
It doesn’t. The cut was due on 6 April 2027, but the Autumn Budget 2026 reversed it, so the cash ISA limit stays at £20,000.
Am I affected if I am over 65?
No. Over-65s keep the full £20,000 cash ISA allowance.
What about stocks and shares ISAs?
The limit is unchanged at £20,000. The reforms are aimed at cash, and partly at moving more money towards investing.
Will cash inside a stocks and shares ISA be taxed?
No. A flat 22% charge on interest from uninvested cash was planned from 6 April 2027, but HMRC confirmed on 29 October 2026 that it won’t take effect. Your investments were never affected.
Can I still hold a money market fund in a stocks and shares ISA?
Yes. The planned rule that a stocks and shares ISA couldn’t be held entirely in money market funds is being revoked along with the rest, at the time of writing.
Can I still move a cash ISA into a stocks and shares ISA?
Yes, and the opposite direction stays open too: the planned block on under-65s moving from stocks and shares into cash won’t take effect.
Key takeaways
All figures are correct at the time of writing and can change, so always check gov.uk for the current numbers. The value of investments can go up and down, and you can get back less than you put in. This is general information, not financial advice. If you are unsure, speak to a regulated financial adviser.